Why Is the Profit and Loss Statement Underused by Clients?
Most owners look at the bottom line and stop. A Schedule C filer sees net profit as the number the IRS taxes. An S corp owner sees what is left after W-2 payroll. Few ask why margins moved or which costs are growing fastest.
That gap is your opening. The P&L can drive clients toward higher-value advisory, provided you explain it in plain language first.
How Can CPAs Use a Profit and Loss Statement for Client Advisory?
Follow these five steps in your next client review:
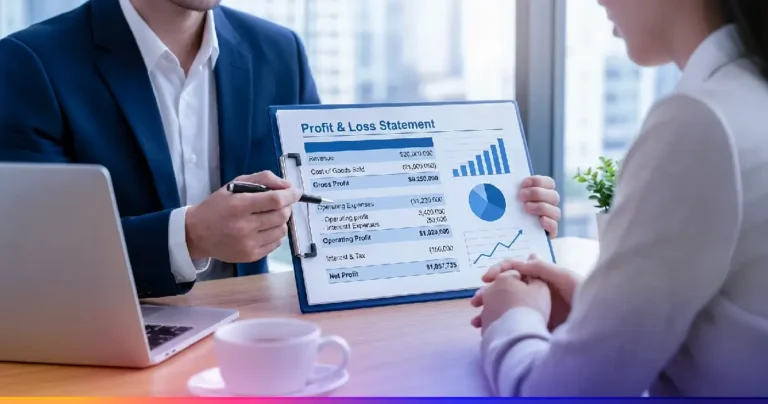
- Separate the types of profit: Show gross profit, operating profit, and net profit side by side. A client with healthy sales but thin net income needs a margin conversation, not a revenue pep talk.
- Split fixed and variable costs: Fixed costs, like rent, stay flat. Variable costs, like materials, move with sales. A growing business benefits from managing variable costs. A seasonal one often needs to tackle fixed costs first.
- Surface hidden costs: Interest on business debt and merchant processing fees quietly erode profit. Compare 1099 contractor spend against W-2 payroll to see where labor costs are heading.
- Benchmark against similar businesses: Clients rarely know what a “normal” P&L looks like in their industry. Use your experience, with identifying details removed, to show them.
- Connect profit to cash flow: A P&L statement shows what happened, not when the money moved. Ask whether the business felt as profitable as the report says. Tight months open the door to cash flow forecasting and budgeting. Read on how firms can prevent month-end bottlenecks affecting clients.
What Should a Profit and Loss Statement Template Include?
A consistent profit and loss statement template keeps these conversations fast and repeatable. At minimum, build in:
- Revenue by stream
- Cost of goods sold
- Gross profit and gross margin
- Operating expenses grouped by category
- Net profit and net margin
- A prior-period or prior-year comparison
How Do You Find Time for Advisory Work?
Capacity is the real constraint. You cannot deliver strong advice if you are still categorizing transactions the night before the meeting. Clean books, produced on time, are what make a useful P&L statement possible in the first place.
This is where an accounting support partner helps. Befree’s remote team handles bookkeeping services, month-end close, and report preparation inside your workflows, so your CPAs spend their hours interpreting the numbers rather than assembling them. Explore our accounting services to see how that support fits your firm.
Ready to Free Up Capacity for Advisory Work?
Let Befree take on the production work so your team can focus on the more value-adding client advisory work. Contact Befree to get started.
FAQs
What is a profit and loss statement?
How is a P&L statement different from a balance sheet?
How often should CPAs review the profit and loss statement with clients?
Can a profit and loss statement help with tax planning?
Yes. Reviewing it before year end helps you spot deductible expenses, estimate liability, and plan around IRS deadlines. You can also read on how to prepare your team before tax season hits.