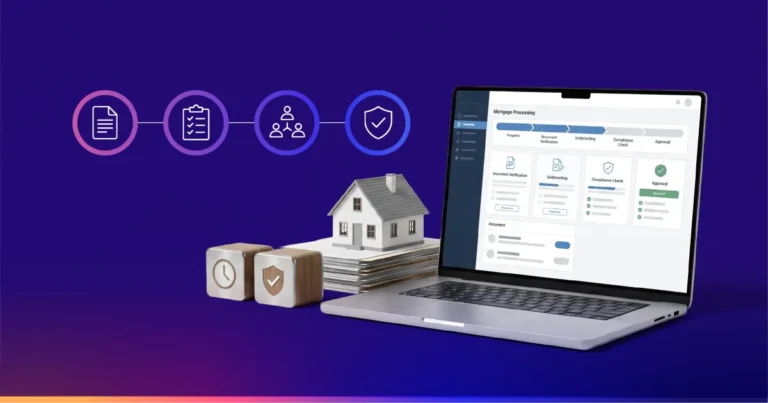
Reducing mortgage processing time comes down to three things: cleaner data at the point of intake, structured case progression, and access to qualified support during peak volume. Firms that address these areas typically shorten mortgage approval time by several working days, without cutting corners on regulatory checks.
For UK mortgage brokers, speed and compliance are often treated as opposing goals. In reality, the firms with the fastest, cleanest mortgage application timeline are usually the ones with the tightest processes, not the ones taking shortcuts.
Where Does the Mortgage Application Timeline Begin to Slow Down?
Most delays do not happen at underwriting. They happen much earlier, in the preparation stage.
Common bottlenecks include:
- Incomplete income evidence: Self-employed applicants, particularly those with income drawn from limited companies, often submit Self Assessment documentation that does not align with what a lender expects to see.
- Inconsistent figures across documents: A mismatch between accounts, tax returns, and bank statements is one of the most common reasons a case is queried back to the broker.
- Manual data entry errors: Rekeying figures from PDFs into application forms introduces avoidable mistakes that trigger further checks.
- Slow document chasing: Firms without a defined follow-up process lose days waiting on clients or accountants to respond.
- Limited case management capacity during busy periods: When application volumes rise, cases simply queue for longer.
5 Workflow Improvements That Can Shorten Mortgage Processing Time
- Standardise income verification for self-employed applicants: Build a consistent checklist for the documents lenders actually require, including SA302s, tax year overviews, and company accounts, so nothing is missing on first submission.
- Reconcile figures before submission, not after: Cross-check income, VAT, and PAYE figures against submitted accounts before a case goes to a lender. Catching discrepancies internally is faster than resolving them mid-application.
- Use templated document request communications: A clear, repeatable request process for missing paperwork reduces the back-and-forth that stretches out the mortgage application timeline.
- Separate case preparation from case advising: Brokers spending time on document chasing and data entry are not spending time advising clients or generating new business. Splitting these functions improves throughput on both sides.
- Build in a pre-submission compliance check: A short internal review, checking documentation completeness and consistency, catches issues before a lender does. This step protects mortgage approval time rather than adding to it.
What Role Does Outsourcing Play in Faster Case Progression?
For many firms, the constraint is not process design. It is capacity.
During peak periods, mortgage brokers and the accountants who support them often cannot absorb additional case preparation work without extending mortgage processing time across their entire pipeline. This is where working with a specialist support partner becomes useful, not as a replacement for advice, but as additional capacity for the preparatory work that sits behind every application.
A qualified support team can handle income verification, document reconciliation, and preparation of accounts information in a format lenders recognise, freeing brokers to focus on client-facing advice. Befree’s mortgage support services are built around exactly this model: structured, compliant support that shortens preparation time without brokers losing oversight of the case.
The result is a faster mortgage application timeline that still meets the same regulatory standard, because the extra capacity is applied to preparation, not to cutting checks.
Conclusion
Reducing mortgage processing time is not about moving faster at every stage. It is about removing the friction that builds up during preparation, reconciliation, and document chasing, so that compliance checks can happen efficiently rather than urgently. Firms that standardise their intake process and bring in qualified support during busy periods consistently see shorter, more predictable mortgage approval times.
If your firm is looking to reduce case turnaround without compromising on compliance, get in touch with Befree to discuss how our mortgage support services can help.