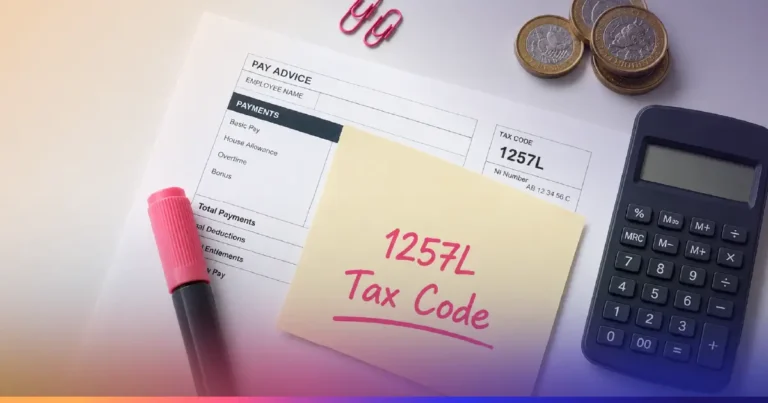
The 1257L tax code is the standard tax code used for most UK employees in the 2026/27 tax year, giving them a tax-free Personal Allowance of £12,570. For payroll teams and the accounting firms managing PAYE on behalf of clients, correctly applying and monitoring this code is not a one-off task. It is a recurring compliance touchpoint that, when handled efficiently, becomes a genuine differentiator for practices managing multiple client payrolls.
This article looks less at the mechanics of the code itself and more at what it means for the accounting firms and payroll departments responsible for getting it right, month after month, across dozens or hundreds of employees.
What Does the 1257L Tax Code Mean for UK Employees?
The numbers in the 1257L tax code represent the employee’s Personal Allowance, divided by ten. The letter L confirms they are entitled to the standard allowance, with no adjustments for benefits, additional income, or underpaid tax from previous years.
For most single-job employees with no complicating circumstances, 1257L is the default. But payroll teams should not treat it as a “set and forget” code. Coding notices change throughout the year as HMRC receives updated information from employers, pension providers, and Self Assessment returns. A firm managing 200 client payrolls might see dozens of code changes in a single month, particularly around the start of the tax year or after annual benefit reporting via P11Ds.
This is where the operational pressure sits. Reviewing every HMRC coding notice, cross-checking it against payroll software, and updating records accurately takes time. For firms already stretched across VAT, CIS, Self Assessment, and Making Tax Digital (MTD) obligations, tax code administration can easily become a bottleneck rather than a routine task.
How Does the 1257L Tax Code Affect PAYE Calculations?
Under PAYE, the 1257L tax code is applied cumulatively by default. This means HMRC and the employer look at total earnings and tax paid from the start of the tax year, rather than treating each pay period in isolation. This cumulative approach smooths out tax deductions across the year, but it also means errors compound if the wrong code is applied early on.
Variants matter too. Payroll teams need to understand the 1257L M1 tax code meaning, since M1 (and its weekly equivalent, W1) indicates a non-cumulative, or emergency, basis. This typically appears when HMRC does not yet have a full picture of an employee’s pay history, often following a job change partway through the tax year. On a non-cumulative code, tax is calculated using only that pay period’s earnings, which can lead to over or underpayment until HMRC issues an updated, cumulative code.
For practices handling payroll at scale, distinguishing between a standard 1257L tax code and an emergency variant across many employees, and knowing when each should trigger a query to HMRC, is a task that benefits from a consistent process rather than ad hoc checking.
How Should Payroll Teams Apply an Updated Tax Code and Address Possible Errors?
When HMRC issues an updated coding notice, either directly to the employee or via the employer’s PAYE system, it should be applied from the next available pay run. Firms managing multiple clients need a reliable process for capturing these notices, since a missed update can mean an employee is taxed incorrectly for several pay periods before the discrepancy is picked up.
Common triggers for a code change away from the standard 1257L tax code include:
- A new company benefit, such as a car or medical cover, reported via P11D or payrolled benefits
- Multiple sources of income, where the Personal Allowance is split or allocated to the main job
- Underpaid tax from a previous year being collected through the current code
- A new starter without a P45, resulting in a temporary or emergency code
Where an error is identified, whether an employee has overpaid or underpaid, HMRC typically issues a P800 calculation, and corrections are made through subsequent payroll runs or a Self Assessment adjustment.
For growing practices, the real challenge is capacity. Manually reconciling coding notices, chasing missing P45s, and correcting historic errors across a large client base is resource-intensive work that pulls skilled staff away from higher-value advisory services. Firms that build structured, repeatable processes around tax code changes, supported by the right payroll software and clear escalation paths, free up capacity to take on more clients without proportionally increasing headcount. This is increasingly relevant as HMRC’s digital reporting requirements, including MTD, continue to expand what practices are expected to manage in real time.
Conclusion
The 1257L tax code will remain the reference point for most UK payroll calculations, but its steady presence on payslips can mask the ongoing administrative work behind it. Coding notices, emergency codes, and mid-year corrections all require attention, and for accounting firms managing payroll across many clients, this adds up to a significant operational load.
Building efficient, well-documented processes around tax code changes is not just about avoiding errors. It is about giving payroll teams the capacity to grow their client base while maintaining the accuracy that firms are judged on. Practices that get this right are better positioned to take on additional PAYE clients without compromising turnaround times or compliance standards.
If your firm is looking to strengthen its payroll processes or explore how Befree can support your practice’s capacity, get in touch with our team.